
For more than 50 years, First Independence Bank has served Detroit communities that too often were overlooked by the broader financial system. We were founded on a simple belief: every family, entrepreneur and neighborhood deserves access to financial opportunity.
Our work is deeply personal and mission-driven. It is the family purchasing its first home. It is the entrepreneur opening a business on a neighborhood corridor. It is the contractor buying equipment to grow a company and create jobs. It is the worker securing reliable transportation to get to work and support a family.
Community banking has never been just about numbers. We know the neighborhoods we serve, the economic realities our customers face, and, often, the story behind a credit application. That understanding allows us to see potential where others see only risk. Sometimes it means saying “yes” when larger institutions say “no.”
The ability to make those investments depends on one essential ingredient: deposits.
Deposits are not idle dollars sitting in an account. They fuel local economic growth. The money one family saves becomes the mortgage another family uses to buy a home. A business account becomes financing for equipment, inventory or expansion. Those funds circulate within communities, creating jobs, opportunity and wealth.
That cycle has been a quiet but powerful force in Detroit’s continued progress.
Today, however, decisions being made in Washington could affect whether those resources remain available in communities like ours all across Michigan.
As Congress continues shaping rules for digital assets, policymakers face an important challenge: encouraging innovation without weakening the banking system that helps finance local economies.
One issue involves payment stablecoins, a form of digital money designed to maintain a stable value, typically one dollar per coin. Used appropriately, stablecoins can offer benefits, including faster, more efficient payments. Innovation should be welcomed when it delivers real value to consumers and businesses.
The question is whether digital asset companies should be allowed to compete with bank deposits while avoiding the responsibilities banks must meet every day.
Congress recognized that distinction in the GENIUS Act by prohibiting payment stablecoin issuers from paying interest simply for holding stablecoins. The intent was clear: stablecoins should function as payment tools, not as lightly regulated substitutes for insured deposit accounts.
Yet a loophole remains. While a stablecoin issuer may not pay interest directly, affiliated exchanges and digital platforms can offer rewards that closely resemble interest payments to customers who maintain stablecoin balances.
To consumers, the difference may appear insignificant. In practice, it is enormous.
Banks operate under stringent safeguards. We maintain capital and liquidity, undergo regular examinations, comply with consumer protection requirements, combat financial crime and support federal deposit insurance. Most importantly, we transform deposits into loans that support families, businesses and local economies.
Stablecoin reserves serve a different purpose. Money backing stablecoins is often invested in Treasury securities and other reserve assets rather than recycled into communities through lending.
That distinction matters for Michigan.
The state’s approximately 70 chartered banks hold roughly $58 billion in deposits. If interest-like stablecoin rewards encourage customers to move money away from banks, billions of dollars could leave Michigan’s deposit base. Fewer deposits ultimately mean less capacity to finance homes, small businesses, automobiles and job creation.
This is not an argument against innovation. Community banks understand change. We have adapted through technological revolutions, evolving customer expectations and shifting economic conditions. We support innovation that improves access, lowers costs and strengthens the financial system.
We oppose a regulatory imbalance that lets one business model benefit from rules another must follow.
America can lead both traditional banking and digital finance. Those goals are not mutually exclusive. But success should come from creating better products and services, not from exploiting gaps in regulation.
When the Senate reconvenes and Congress continues considering digital asset legislation, including the CLARITY Act, Michigan’s congressional delegation will have an opportunity to address this issue. The solution is straightforward: permit legitimate customer rewards while preventing arrangements that effectively pay interest for holding stablecoins.
That approach would preserve innovation while maintaining the distinction Congress already recognized between a payment product and a bank deposit.
First Independence Bank stood with Detroit through difficult times and through its resurgence. We also intend to help shape the future of finance. But that future should strengthen communities, not quietly drain the deposits that help families buy homes, entrepreneurs build businesses and neighborhoods create lasting wealth.
Detroit and the state of Michigan deserve both innovation and a financial system that continues investing in its future.
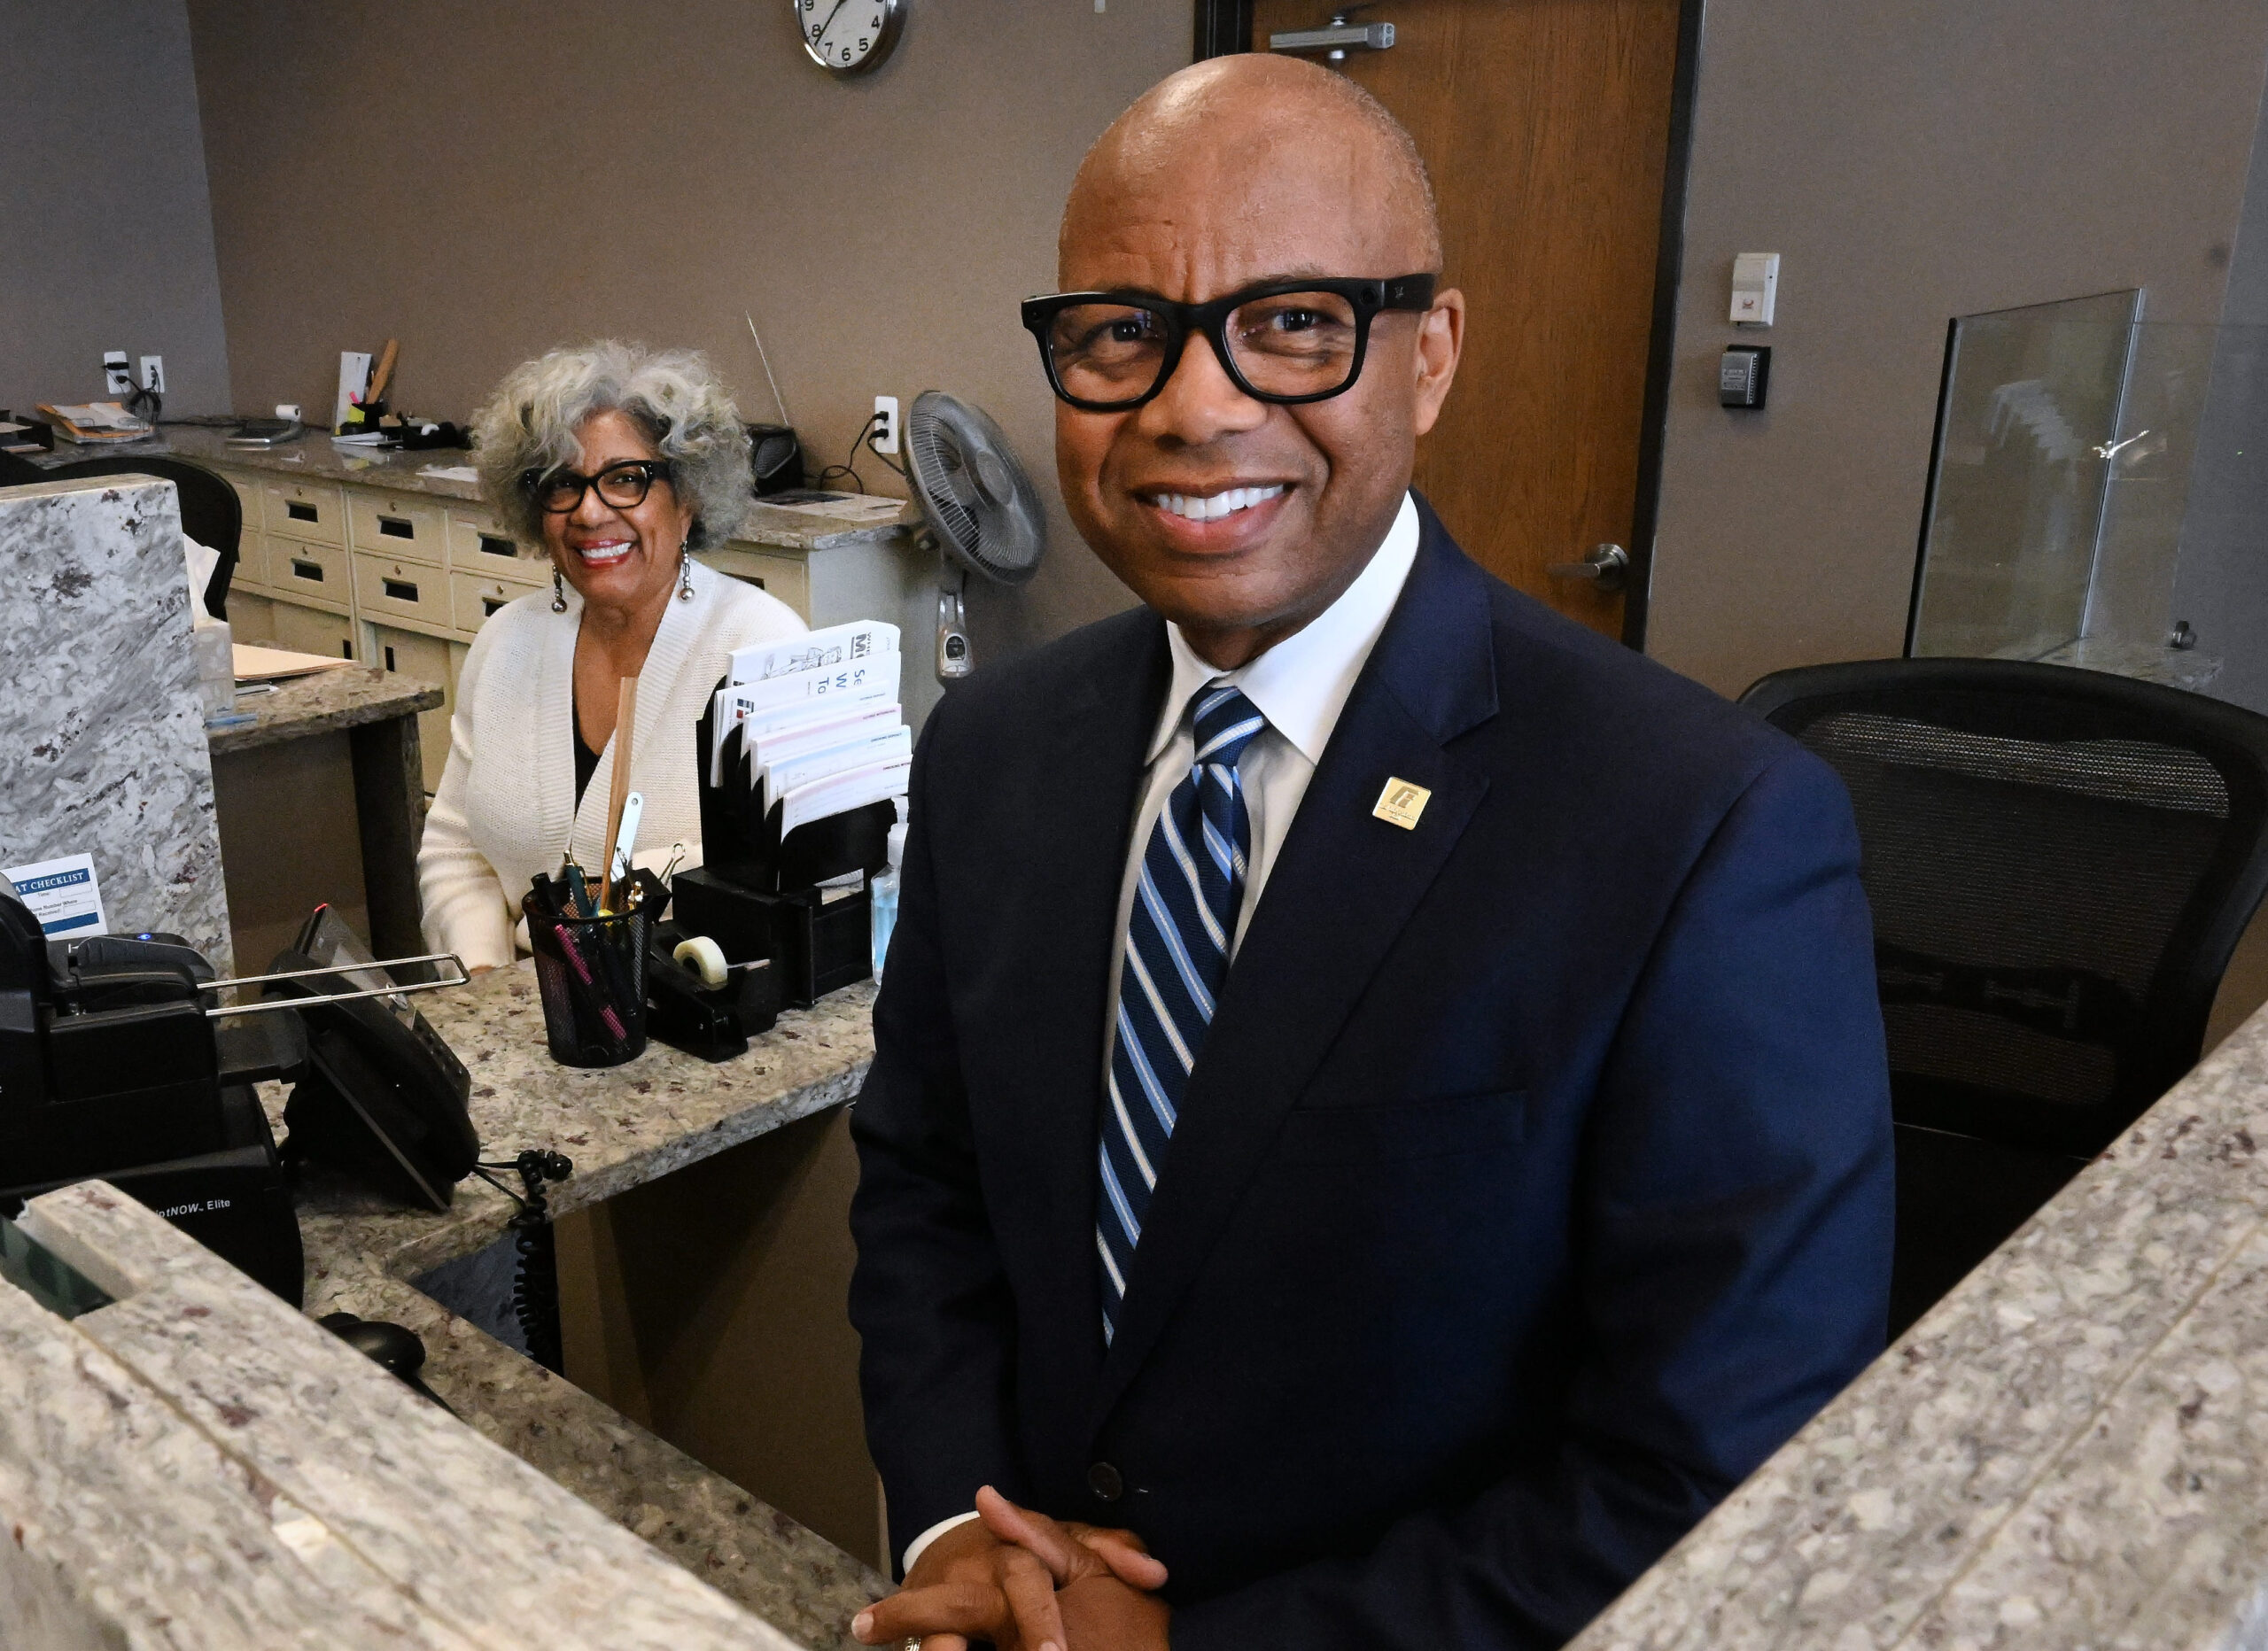
Kenneth Kelly is chairman and CEO of First Independence Bank and chair of the American Bankers Association.
This article originally appeared on The Detroit News: Michigan needs financial innovation without sacrificing local lending | Opinion
Reporting by Kenneth Kelly / The Detroit News
USA TODAY Network via Reuters Connect

Michigan needs financial innovation without sacrificing local lending | Opinion added by admin on
View all posts by admin →